Retirement Income Planning for a 72-Year-Old Oregon Couple With $3 Million in an IRA
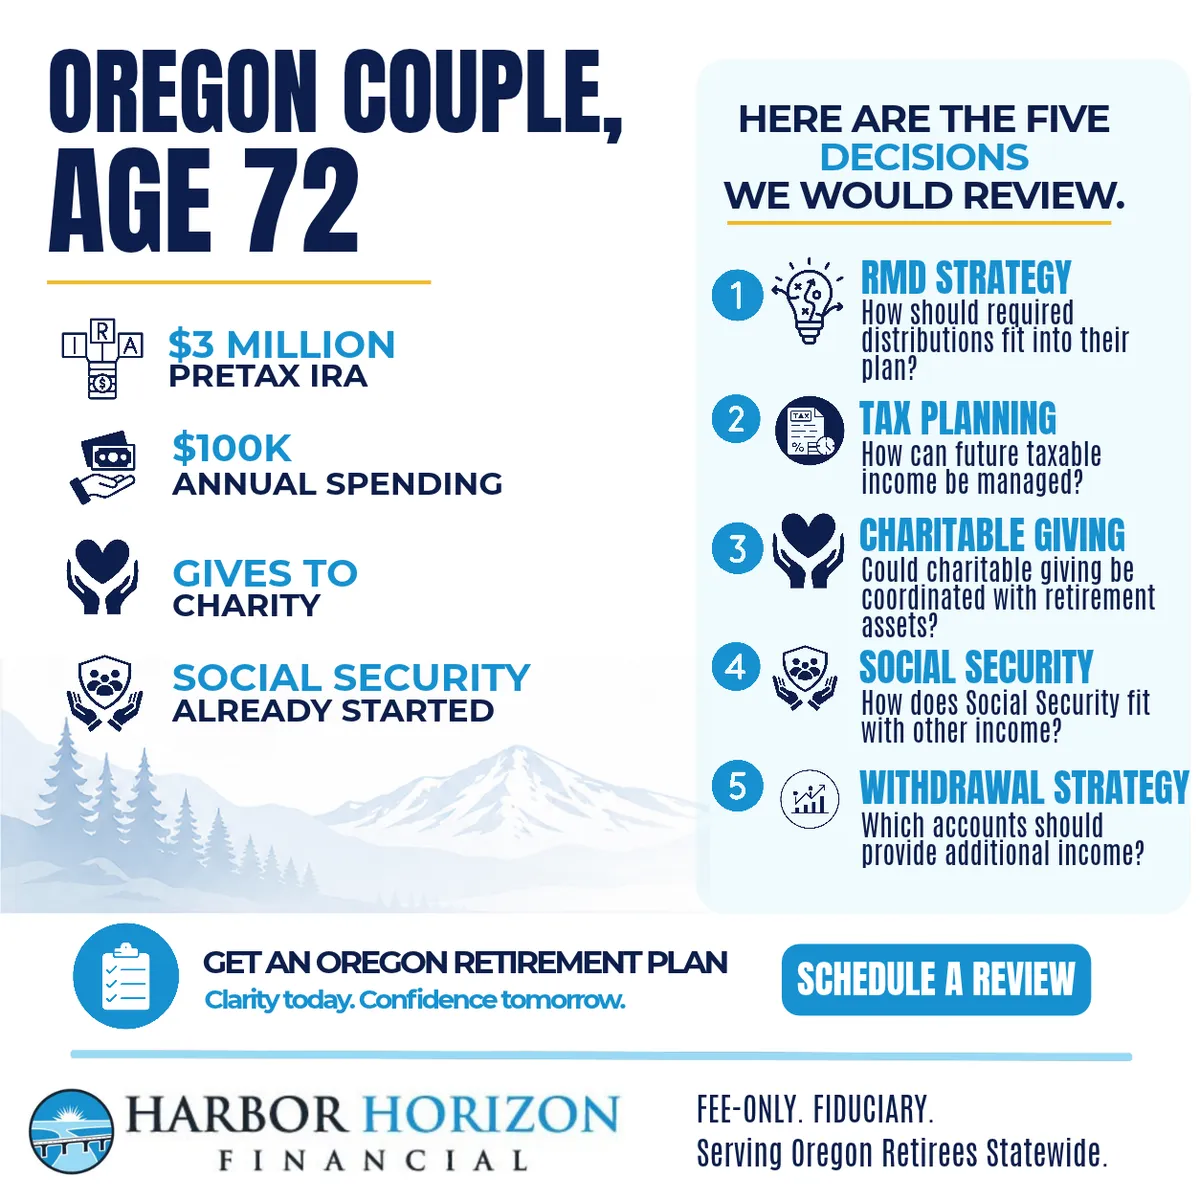
For this hypothetical Oregon couple, retirement is already underway. They're both 72, have accumulated $3 million in a traditional IRA, spend approximately $100,000 annually, and are collecting Social Security.
They're in a strong financial position, but the size of their pretax retirement account presents some tax planning challenges.
With required minimum distributions (RMDs) beginning at age 73, they could soon be required to withdraw more from their IRA than they actually need to spend. Those withdrawals could increase their income taxes and potentially their Medicare premiums.
Here's how we would approach their situation.
Household Snapshot
Age: Both 72
Retirement savings: $3 million in a traditional IRA
Annual spending: $100,000
Social Security: Both spouses have started collecting
Charitable giving: Regular contributions to charitable organizations
Location: Oregon
Primary goals: Maintain their lifestyle, manage taxes, support charitable causes, and preserve assets for the future
1. Prepare for Required Minimum Distributions
Under current law, this couple will generally begin taking RMDs at age 73.
Assuming the entire $3 million is held in one spouse's traditional IRA, and the applicable year-end balance remains $3 million, their first RMD would be approximately $113,000 using the standard IRS Uniform Lifetime Table.
The actual amount will depend on the IRA balance on December 31 of the preceding year and the applicable IRS distribution factor.
This creates a potential issue.
They spend approximately $100,000 annually, and Social Security already covers a portion of those expenses. Their required IRA withdrawal could therefore exceed what they need for living expenses.
Even if they don't need all the money, the taxable portion of their RMD generally gets added to their income.
Our recommendations could include:
Estimate their upcoming RMDs and the resulting federal and Oregon income taxes.
Review whether taking IRA distributions or completing partial Roth conversions before RMDs begin makes sense, based on their current and projected tax brackets.
Determine how much of each RMD should be used for living expenses, charitable giving, and taxes.
Reinvest any remaining distributions in a taxable brokerage account rather than allowing unnecessary cash to accumulate in the bank.
We would also review their Medicare premiums. Higher income can trigger Income-Related Monthly Adjustment Amounts (IRMAA), increasing Medicare Part B and Part D premiums.
2. Use Qualified Charitable Distributions (QCDs) for Tax Planning
Because this couple already gives to charity, one of the first strategies we'd review is using Qualified Charitable Distributions (QCDs).
A QCD allows someone age 70½ or older to transfer funds directly from an eligible IRA to a qualifying charitable organization.
When completed correctly, the distribution can be excluded from taxable income. Once RMDs begin, a QCD can also count toward satisfying the annual RMD.
Here's an example:
Suppose the couple's required distribution is $113,000 and they normally donate $20,000 annually to charity.
Instead of taking the full IRA distribution into their bank account and then donating $20,000, they could transfer the $20,000 directly from the IRA to their qualifying charities.
Their distributions could look like this:
Distribution | Amount |
Total RMD | $113,000 |
Qualified Charitable Distribution | $20,000 |
Remaining IRA distribution | $93,000 |
Amount generally excluded from taxable income through the QCD | $20,000 |
Assuming the entire IRA is pretax and the QCD meets IRS requirements, only the remaining $93,000 would be included in taxable IRA distributions.
This strategy can be especially useful for retirees who take the standard deduction because the QCD does not require them to itemize deductions.
A few important details:
The distribution must go directly from the IRA custodian to an eligible charitable organization.
Donor-advised funds generally do not qualify for QCDs.
The couple cannot also claim a charitable deduction for the amount excluded from income.
Each spouse must meet the eligibility requirements and make QCDs from their own eligible IRA.
QCDs should generally be coordinated before taking RMD withdrawals, because distributions already taken cannot be retroactively treated as QCDs.
For Oregon retirees with substantial pretax retirement savings, QCDs can potentially reduce both federal and state taxable income while supporting causes they already care about.
3. Coordinate Social Security and IRA Withdrawals
Since both spouses are already receiving Social Security, we would review their annual benefits alongside the income they expect to withdraw from their IRA.
For example, suppose they receive a combined $60,000 annually in Social Security benefits.
With annual spending of $100,000, Social Security covers a substantial portion of their expenses before considering taxes.
However, their upcoming RMDs could be more than the additional amount needed to fund their lifestyle.
We would recommend creating an annual withdrawal plan that:
Accounts for Social Security income and expected living expenses.
Uses required IRA distributions to fund the remaining spending need.
Sets aside sufficient cash for federal and Oregon income taxes.
Reinvests excess withdrawals in a taxable investment account.
Reviews the taxable IRA balance annually to project future RMDs.
It's also worth understanding how Oregon treats retirement income.
Oregon does not tax Social Security benefits, but distributions from traditional IRAs are generally subject to Oregon income tax.
Social Security benefits can still be taxable at the federal level, depending on the household's total income.
For a couple with a large traditional IRA, this makes it particularly important to estimate taxes before deciding how much to withdraw.
4. Review Their Long-Term Tax Exposure
While this couple has accumulated substantial retirement savings, most of their money is in a pretax account.
That means withdrawals will generally be taxable, and the remaining IRA balance may continue growing even as they take distributions.
We would review whether there are opportunities to reduce their long-term tax exposure.
Potential recommendations include:
Partial Roth conversions: Determine whether converting a portion of their IRA to a Roth IRA makes sense before their RMDs begin. We would compare the taxes paid today against potential future tax savings.
Annual tax projections: Estimate taxable income before year-end to identify opportunities and avoid unnecessary tax surprises.
Medicare planning: Review how IRA distributions and Roth conversions could affect Medicare premiums, generally using income reported two years earlier.
Beneficiary planning: Review who will inherit the IRA and the potential income tax consequences for their beneficiaries.
Because they're Oregon residents, we'd also review their estate plan.
Oregon's estate tax threshold is significantly lower than the federal estate tax exemption. Depending on their other assets, a $3 million IRA alone could make Oregon estate tax planning relevant.
We would want to review their total estate, beneficiary designations, and existing estate planning documents.
The Main Takeaway
For this Oregon couple, the biggest opportunities are likely in tax planning and managing their large traditional IRA.
At age 72, they have an opportunity to evaluate Roth conversions before required distributions begin. Once RMDs start, QCDs could be a particularly effective way to continue their charitable giving without unnecessarily increasing taxable income.
We would prioritize estimating their upcoming RMDs, reviewing their charitable giving strategy, and preparing a withdrawal plan that accounts for Social Security, taxes, and their actual spending needs.
These are the types of decisions that can make a meaningful difference over a 20 or 30-year retirement.
Want to See How Your Numbers Fit Together?
If you're approaching retirement or already retired in Oregon, Harbor Horizon Financial helps families make informed decisions about retirement income, taxes, investments, and estate planning.
This hypothetical scenario does not represent a specific client. Certain details may have been created or modified for illustrative purposes and to protect privacy. This content is for informational and educational purposes only and should not be construed as individualized financial, tax, or legal advice. The information reflects general planning concepts and may not be appropriate for your specific situation. Consult a qualified financial advisor, tax professional, or attorney before making financial decisions. Harbor Horizon Financial is a Registered Investment Adviser in the state of Oregon. Registration does not imply a certain level of skill or training.